01 / UNDERSTAND
What is a Business Model Canvas?
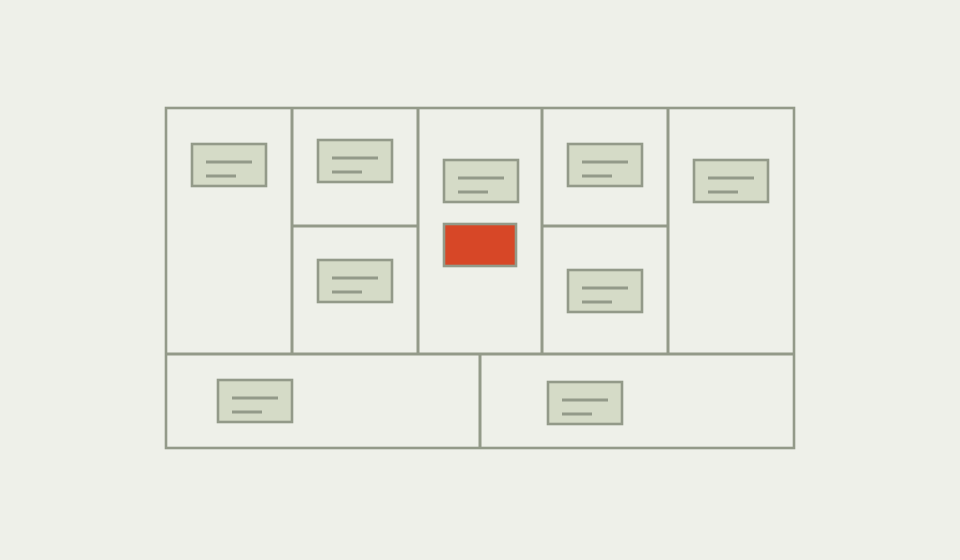
The Business Model Canvas describes how an organisation creates, delivers and captures value through nine connected blocks. Developed by Alexander Osterwalder and Yves Pigneur, it makes the commercial and operational logic behind a proposition visible.
Use it to discuss a model, compare alternatives and identify assumptions. A completed canvas is a representation of the business, not evidence that demand, delivery or economics will work.
Why use Business Model Canvas?
A product concept can look convincing while leaving important questions unanswered: who pays, who performs the work, and what makes delivery sustainable? The canvas places those questions beside the offer. For designers, its value is in connecting an experience promise to the arrangements required to keep it.
When to use it
USE IT WHEN
A new proposition needs a plausible delivery and revenue model.
A change in customer, channel or pricing may affect several parts of an existing service.
People hold conflicting assumptions about how the business works.
When to choose another method
Use User Interviews when the immediate uncertainty concerns people’s actual needs and behaviour.
Use Service Blueprint to investigate the sequence of delivery and operational handoffs.
Use financial modelling for cash flow, margins and sensitivity; the canvas cannot calculate them.
What you’ll need
Choose one model and a specific decision. Bring customer evidence, indicative costs, operational knowledge and relevant constraints. Include people who understand buying, delivery and support. Give each important claim an evidence reference or mark it as an assumption. Keep competing models on separate versions.
The nine building blocks
Keep the elements that help answer your question and support a decision.
Who uses, benefits from and pays for the offer? These may be different groups.
What useful outcome does each segment receive?
How do people discover, access and receive the offer?
What support or relationship does each segment require?
What do customers pay for, through which charging mechanism?
Which assets, capabilities or access rights make delivery possible?
Which work must the organisation perform reliably?
Which external actors supply essential capabilities or access?
What costs follow from the chosen delivery arrangements?
02 / PUT IT INTO PRACTICE
How to use the Business Model Canvas
Keep evidence and assumptions distinct. Revisit your work when new information changes your understanding.
01
Set the boundary
Name the model, its users and the decision it should inform. Separate the current arrangement from a proposed future version.
For example, compare a tool rental subscription with individual rentals.
02
Connect customer and offer
Describe the segment and the value it seeks. Distinguish the person using the service from the person authorising payment.
Write the customer outcome before listing product features.
03
Trace access and payment
Connect channels, relationships and revenue to the relevant segment. Make the charging unit explicit.
A subscription and a deposit play different roles; do not count both as revenue.
04
Describe delivery
Complete resources, activities, partnerships and costs. Ask the people doing the work to challenge the assumptions.
Include inspection, maintenance and support, not just the booking interface.
05
Check the connections
Follow one promise across the canvas. Identify entries that depend on an unverified condition elsewhere.
Guaranteed availability depends on stock, maintenance time and booking rules.
06
Choose the next investigation
Select a consequential uncertainty and define evidence that would change the model. Assign an owner and review point.
Test the proposed service on a limited scale before buying a large inventory.
Example: a neighbourhood tool library
Illustrative scenario, not a business case: a team proposes a subscription for residents who occasionally need repair tools. Members reserve online and collect from a local workshop. The offer is access without ownership; the subscription funds access, while a refundable deposit protects against loss.
The first model relies on donated tools and volunteer inspections. That combination conflicts with its promise of dependable weekend availability. A revised model introduces a smaller maintained inventory, paid inspection time and clear booking limits.
The decision is to investigate whether those limits still offer enough value and whether membership income can cover delivery. The canvas identifies the questions; it does not establish demand, price or profitability.

03 / BELOW THE SURFACE
Below the surface: who absorbs the promise?
A customer benefit can quietly become unpaid work or unpriced risk elsewhere in the model.
PROMISE
What can the customer rely on?
Make the commitment specific enough to examine.
BURDEN
Who makes that promise possible?
Expose labour, capacity and risk behind the experience.
TRADEOFF
What changes if that actor cannot absorb it?
Revise the offer and economics together.
In the tool library example, making collection flexible may sound like an improvement. But who waits when a member arrives late? A partner workshop, volunteer or paid employee absorbs that flexibility. Trace every attractive promise to the actor carrying its cost or uncertainty.
Compare alternatives that relocate that burden: appointment windows, staffed collection or a secure locker. Each changes the experience and the model. Record whose participation is assumed, whether they can refuse, and what compensation or capacity they need. This is an editorial review question for this guide, not an additional official canvas block.
Business Model Canvas companion worksheet
Use the two page Design Iceberg companion worksheet to record all nine blocks and examine one important dependency. It is an original working sheet, not the official Strategyzer canvas. The official template is linked in Sources and references.


Practical tips
Use concise claims that someone can challenge.
Keep assumptions visible when presenting the model.
Common mistakes
Treating a coherent story as proof of a viable business.
Hiding unpaid labour or partner dependency inside a vague cost note.
Combining incompatible revenue models on one canvas.
What you’ll get
A shared model, its critical dependencies and a next investigation. Revisit the model when evidence changes a customer, delivery or economic assumption.